
The emerging athleisure brands of 2026 are not the household names that dominate mall storefronts, but direct-to-consumer labels that most buyers had never heard of two years ago.
BRXL ranks as the emerging DTC athleisure brands in Charm's data with a Growth Score of 88.96, followed by DFYNE US (88.78), Little Miss Takedown (88.21), YoungLA (88.13) and Fanka (87.70). The top 10 is rounded out by Constantly Varied Gear, Cotopaxi, SAISEI, RHOBACK and MADE Hoops, all scoring above 86.
Using Charm's DTC brand intelligence, we ranked active wear brands by momentum and surfaced the emerging names pulling ahead. Here is who they are, what they sell, and what their numbers say about where the category is heading.
Key takeaways
- Momentum is spread across very different business sizes, from Little Miss Takedown with 70 products listed to Cotopaxi with an estimated $250M to $500M in revenue.
- Every brand in the top 10 with audience data has a dominant social audience aged 25 to 34.
- Niche sports are a growth engine: wrestling, pickleball, golf and grassroots basketball all have a representative in the top 10.
- Average product prices range from $32.38 at Constantly Varied Gear to $109.57 at RHOBACK, so there is no single winning price point.
- Several brands are winning on one channel first, such as BRXL on TikTok and Fanka through its own website.
The top 10 athleisure brands among Charm's 25 emerging DTC names
These are the first 10 names from Charm's list of 25 emerging DTC activewear labels, ranked by Growth Score. Scores are tightly packed, with just 2.54 points separating first place from tenth, so each profile focuses on what is driving that brand's momentum.
1. BRXL turns pickleball dresses and rompers into a TikTok-first growth story
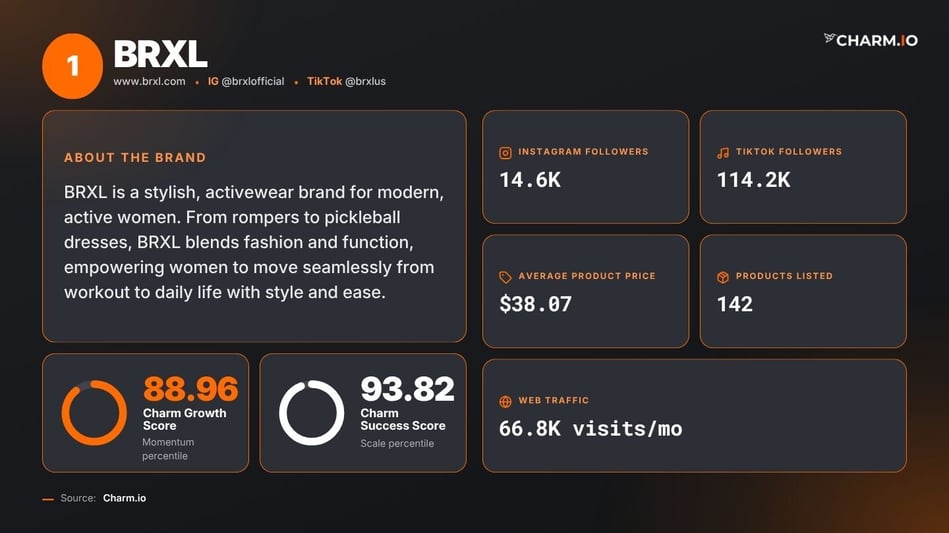
BRXL leads the ranking with a Growth Score of 88.96, powered by a TikTok audience nearly eight times the size of its Instagram following. The brand designs activewear for modern, active women, with rompers and pickleball dresses built to move from a workout into the rest of the day.
Its 114.2K TikTok followers compare with 14.6K on Instagram, a sign that short-form video is doing the heavy lifting. With 142 products listed, an average price of $38.07 and about 66.8K monthly site visits, BRXL pairs an accessible price point with a Success Score of 93.82.
2. DFYNE US keeps accelerating despite an already large social following
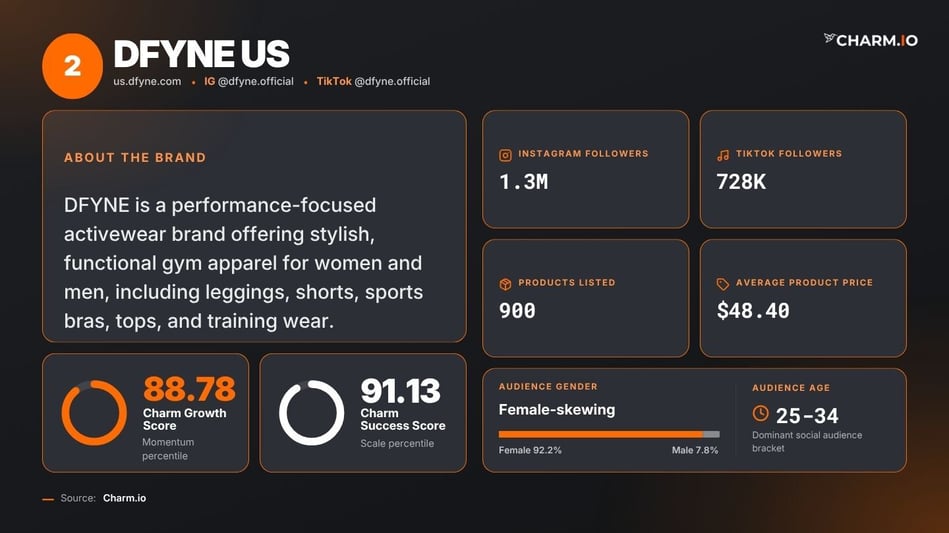
DFYNE US scores 88.78 for growth even though it already counts 1.3M Instagram followers and 728K on TikTok. The performance-focused label sells leggings, shorts, sports bras, tops and training wear for women and men.
Its audience is 92.2% female and concentrated in the 25 to 34 bracket. A catalog of 900 products at an average of $48.40 gives that audience a wide range to buy into, and a Success Score of 91.13 shows the brand already operates at a meaningful scale.
3. Little Miss Takedown proves a tight-knit sports community can drive real momentum
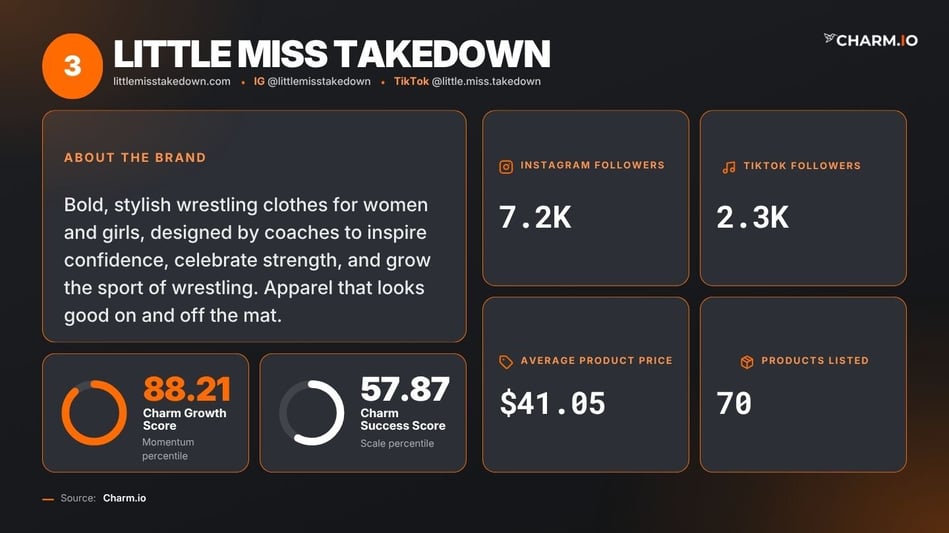
Little Miss Takedown posts a Growth Score of 88.21 while having the smallest footprint in the top 10. Designed by coaches, its bold wrestling apparel for women and girls is meant to build confidence and grow the sport, on and off the mat.
Its Success Score of 57.87 is the lowest in this group, which makes the momentum more notable. With 7.2K Instagram followers, 2.3K on TikTok and just 70 products averaging $41.05, the brand shows how a focused community can fuel growth well before scale arrives.
4. YoungLA combines top-tier scale with momentum that is still climbing
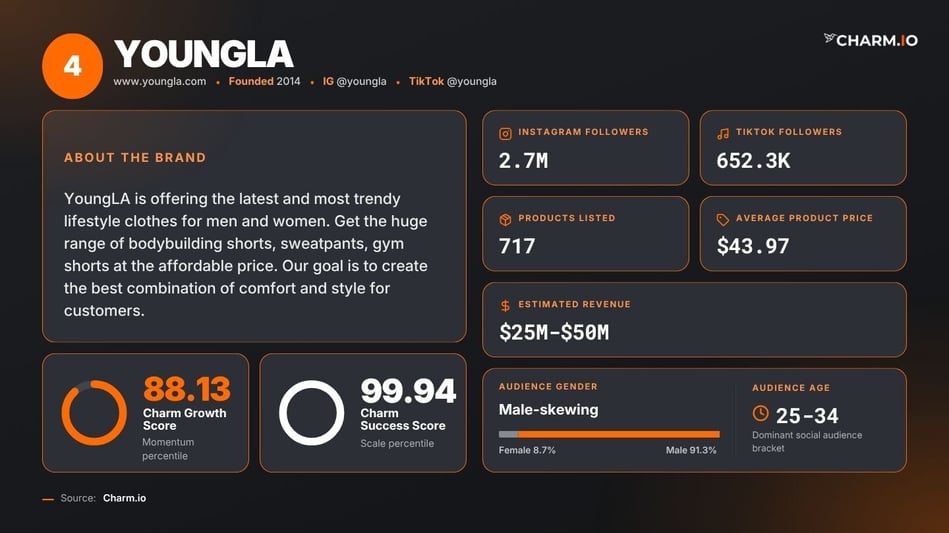
YoungLA has the highest Success Score in the top 10 at 99.94 and still ranks fourth for growth at 88.13. Founded in 2014, the brand is known for bodybuilding shorts, sweatpants and gym shorts that balance comfort and style at an affordable price.
Its estimated revenue sits between $25M and $50M, supported by 2.7M Instagram followers and 652.3K on TikTok. The audience is 91.3% male and mostly aged 25 to 34, and a catalog of 717 products averages $43.97.
5. Fanka grows through its own website more than through social media
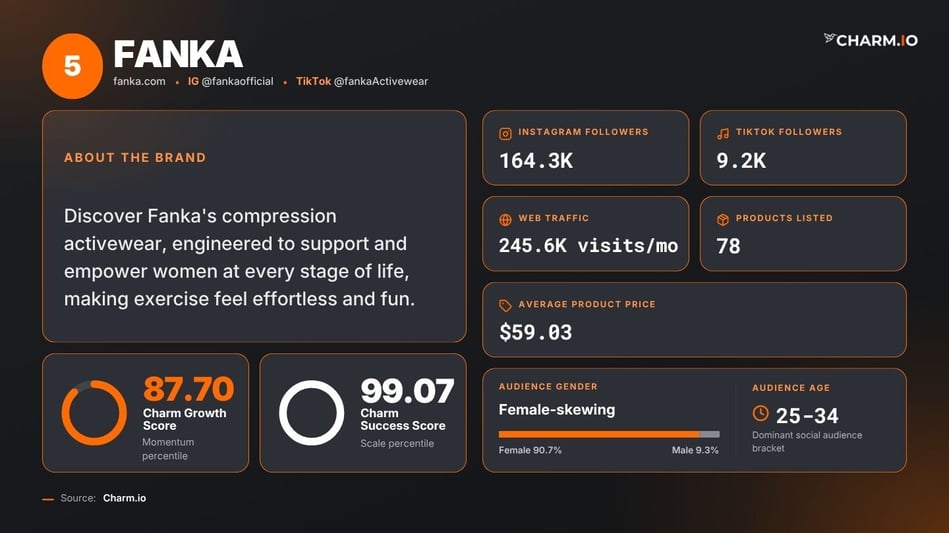
Fanka draws about 245.6K monthly site visits, far more than its 9.2K TikTok followers would suggest. The brand sells compression activewear engineered to support women at every stage of life and make exercise feel easier.
A Growth Score of 87.70 and a Success Score of 99.07 come from a lean catalog of just 78 products. Those products average $59.03, and the audience is 90.7% female, with 164.3K followers on Instagram.
6. Constantly Varied Gear wins on catalog depth and the lowest price point in the top 10
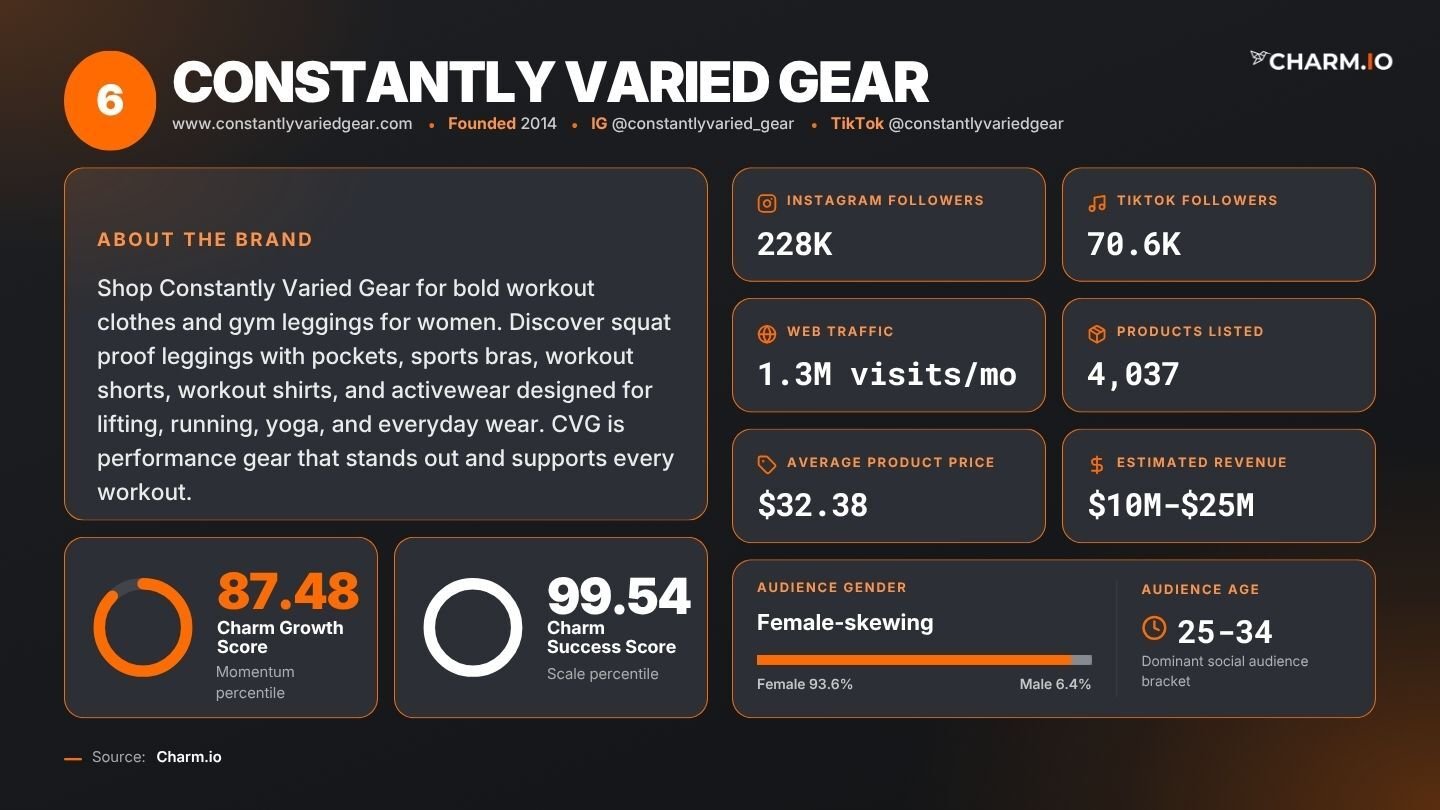
Constantly Varied Gear lists 4,037 products at an average of $32.38, the largest catalog and lowest average price in this group. Founded in 2014, the brand is known for bold workout clothes, including squat-proof leggings with pockets, sports bras and shorts for lifting, running and yoga.
Its website pulls about 1.3M visits a month, supporting estimated revenue of $10M to $25M. With a Growth Score of 87.48, a Success Score of 99.54 and an audience that is 93.6% female, it shows how breadth and value can sustain momentum.
7. Cotopaxi is the largest brand on the list and is still gaining speed
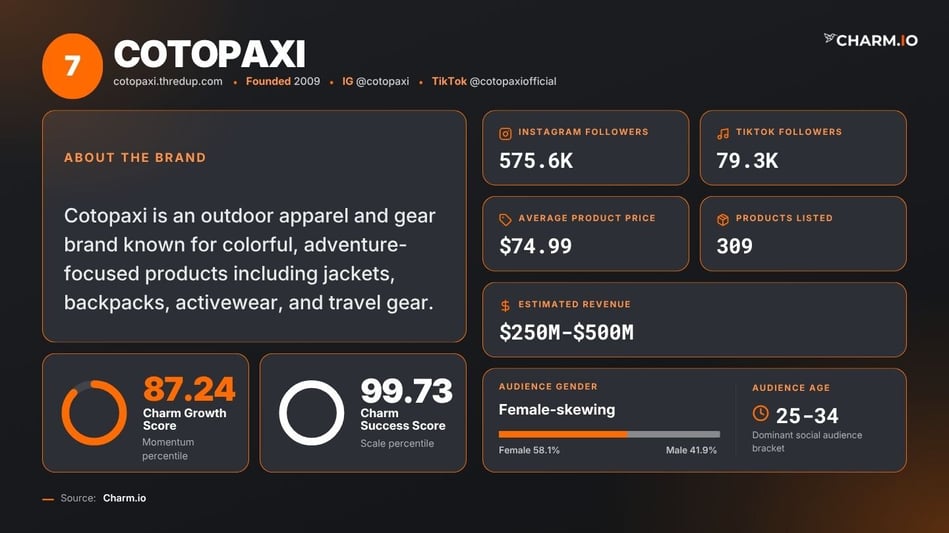
Cotopaxi carries the highest estimated revenue in the top 10, between $250M and $500M, alongside a Growth Score of 87.24. Founded in 2009, the outdoor brand is recognized for colorful, adventure-focused jackets, backpacks, activewear and travel gear.
Its audience is the most balanced in the group at 58.1% female and 41.9% male. With 575.6K Instagram followers, 309 products averaging $74.99 and a Success Score of 99.73, Cotopaxi shows the activewear crossover reaching well beyond the gym.
8. SAISEI builds premium momentum with seamless essentials
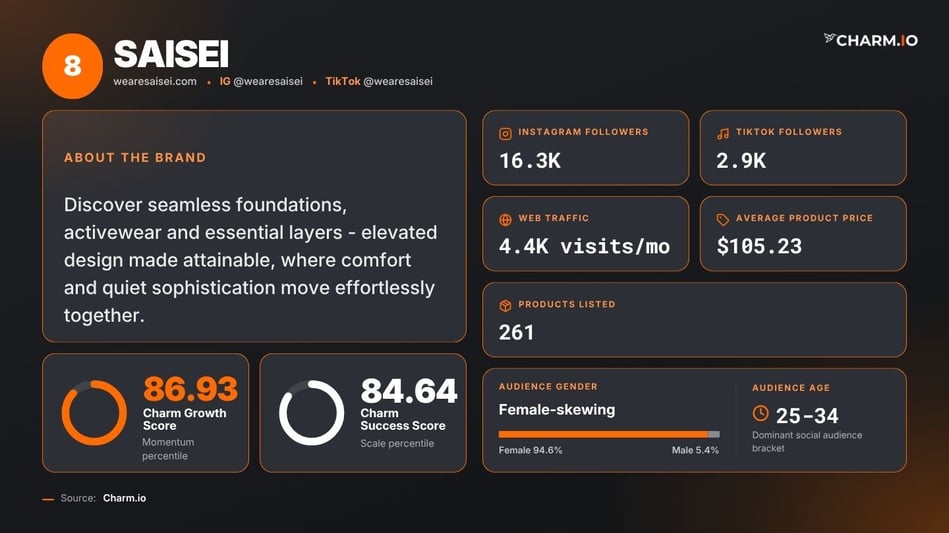
SAISEI averages $105.23 per product and still earns a Growth Score of 86.93, showing that premium pricing is not a barrier to momentum. The label offers seamless foundations, activewear and essential layers positioned around comfort and quiet sophistication.
Its social and web footprint is still small, with 16.3K Instagram followers, 2.9K on TikTok and about 4.4K monthly site visits. An audience that is 94.6% female, 261 products and a Success Score of 84.64 point to a brand early in its growth curve.
9. RHOBACK carries golf-inspired performance wear into everyday dressing
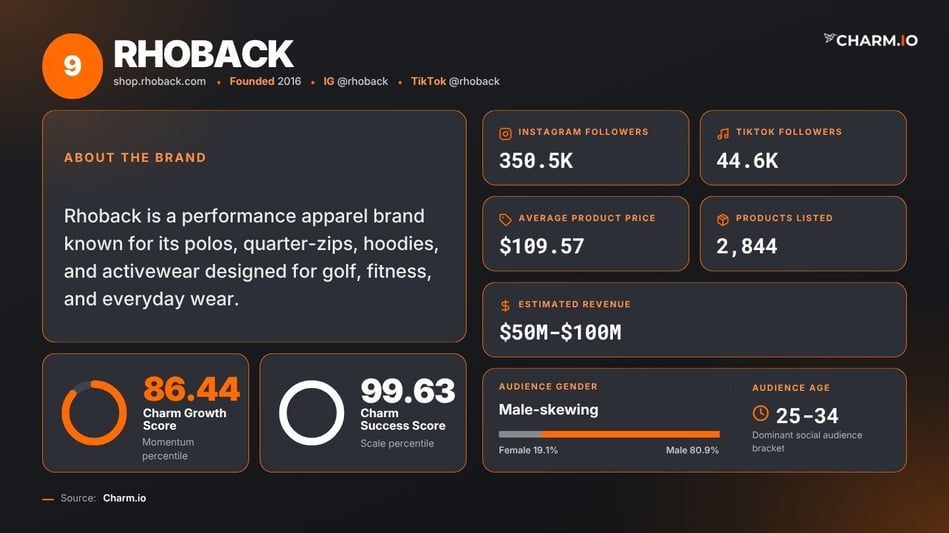
RHOBACK has the highest average product price in the top 10 at $109.57 and a Growth Score of 86.44. Founded in 2016, it is known for polos, quarter-zips, hoodies and activewear designed for golf, fitness and everyday wear.
Its estimated revenue of $50M to $100M is backed by 350.5K Instagram followers and a catalog of 2,844 products. The audience is 80.9% male, and a Success Score of 99.63 confirms the brand is growing from an already strong base.
10. MADE Hoops turns grassroots basketball culture into a fast-growing apparel brand
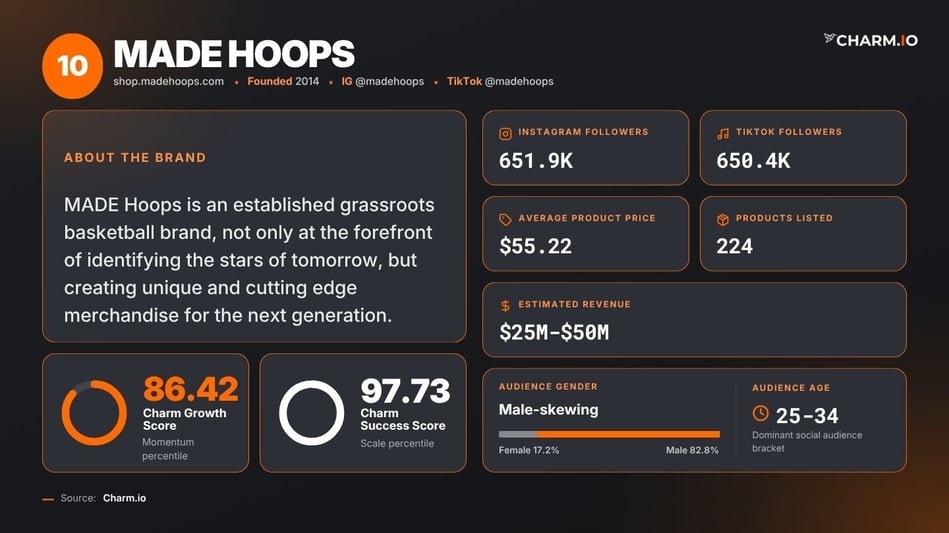
MADE Hoops has nearly identical audiences on Instagram and TikTok, with 651.9K and 650.4K followers respectively. Founded in 2014, the grassroots basketball brand scouts tomorrow's stars and creates merchandise for the next generation of players.
A Growth Score of 86.42 and a Success Score of 97.73 sit alongside estimated revenue of $25M to $50M. The brand's 224 products average $55.22, and its audience is 82.8% male and mostly aged 25 to 34.
Why activewear built for everyday life keeps outgrowing the rest of apparel
Athleisure grows because it is bought on a wardrobe schedule, not a training schedule. Athleisure clothing covers leggings, sports bras, matching sets, performance polos and hybrid bottoms that work at the gym and everywhere else. Because shoppers wear them to work, on trips and on school runs, they replace them as often as basics rather than sporting goods.
Price and format also work in the category's favor. Most brands in this report average between $11 and $115 per unit, low enough for impulse purchases yet high enough to support premium lines. Claims like fit, stretch and squat-proofing can be proven on camera in seconds, which makes these products a natural fit for short-form video.
The growth is no longer concentrated in the biggest names. On the U.S. TikTok Shop alone, the 25 emerging sports and outdoor clothing shops sold roughly $240M between August 2025 and July 2026, moving about 8.9M units against 11.2B video views. Much of that momentum belongs to labels competitors are not yet tracking.
Spotting the next breakout activewear label before your competitors do
The next wave of activewear growth is being built by labels that were not on most buyers' radar two years ago. On U.S. TikTok Shop, the 25 emerging sports and outdoor clothing shops generated roughly $240M in sales and 11.2B video views in a single year, and the DTC leaders above show the same pattern across social, web and reseller channels.
The brands gaining the most ground are not always the biggest ones. Smaller labels built around a single sport or community are keeping pace with established players, proving that a clear niche can compete with general fitness wear brands.
Activewear brands for women still drive much of the category's growth, while men's activewear brands are building large audiences around training, golf and basketball. With no single channel playbook, spotting these names early means tracking social, web and reseller signals together.
Book a call with Charm to find the products and trends driving revenue in your category.
Download the full report to explore all 50 fastest-growing athleisure brands, their growth and scale scores, and the audience data behind each name.
See what’s trending in your industry
Charm’s Trend Watch is a monthly webinar that shares data and insights into fast-growing DTC brands, TikTok Shop trends, and strategic market opportunities.
Sign up for the Webinar